Who would manage your clients’ finances if they were hospitalized? Who would arrange care if they could no longer live independently? And who could make important decisions on their behalf if they were unable to?
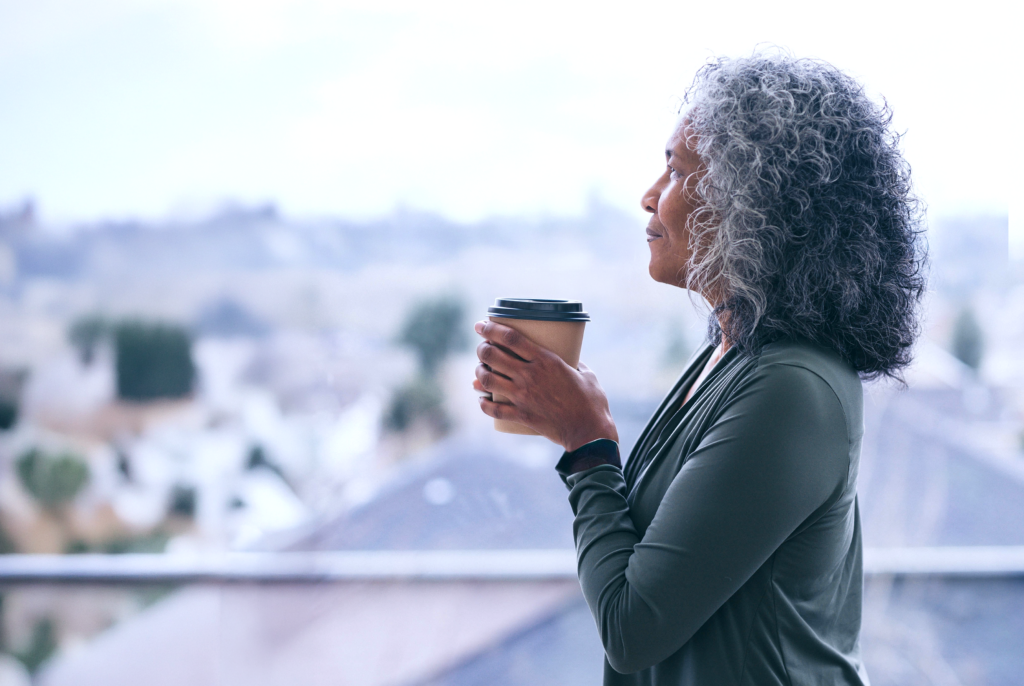
These questions deserve a place in retirement conversations, particularly with women, who tend to live longer than men and some of whom may not have a spouse, adult children, or close family members they can rely on as their needs change.
According to an analysis of U.S. Census Bureau data, nearly 11 million women age 65 and older lived alone in 2025.1
And while living alone doesn’t necessarily mean lacking support, it raises important considerations about preparing for the later stages of retirement.
There’s also an opportunity for financial professionals to help women who may not be receiving guidance today. In a Mather Institute survey of older adults aging without a spouse or adult children they can depend on, only 31% had developed a financial plan.²
As more women prepare for retirement on their own, financial professionals have an opportunity to help them prepare for the realities of a self-reliant retirement.

Why self-reliant retirement requires more than financial independence
Women who have spent years managing their own finances may feel well prepared for retirement. But having sufficient savings is only one part of maintaining independence as they age.
Consider a divorced woman approaching retirement whose adult children live across the country. Or a woman who has never married and has no children. Both may have accumulated substantial retirement savings, yet have important decisions to make about how they’ll manage changing health, housing, and care needs.
This is where financial professionals can provide valuable guidance by helping women think through circumstances they might not have considered and identifying ways to prepare financially.

Help women prepare for the possibilities ahead
-
Establish a dependable retirement income.With no second household income to rely on, covering essential expenses throughout retirement becomes especially important. Help clients evaluate Social Security benefits, retirement savings, and other income sources. An annuity offering guaranteed lifetime income may help provide a dependable source of income while allowing other assets to remain available for unexpected needs.
-
Prepare for future care expenses.Without a spouse or nearby family to provide assistance, women may need to rely more heavily on paid caregiving services. Discuss potential long-term care needs, available funding options, and how clients would cover the cost of assistance while maintaining their other financial obligations.
-
Evaluate housing decisions.A home that suits a client’s lifestyle today may become less practical as she ages. Help her consider the financial implications of home modifications, in-home assistance, downsizing, or moving to a community that offers additional services.
-
Identify a trusted support network.Encourage clients to think about who could help manage their affairs or make decisions if they become unable to do so. Work with their estate planning attorneys and other qualified professionals to help ensure appropriate powers of attorney, health care directives, and other arrangements are in place.

Reach women who may not realize they need your guidance
Helping existing clients prepare is a natural starting point. But what about women who aren’t currently working with a financial professional?
Some may be comfortable managing their own money and see little reason to seek advice. Others may associate financial professionals primarily with investing or wealth management, without realizing the broader role they can play in preparing for retirement.
To help these women recognize the value of your services, focus your outreach on the situations you can help them prepare for, rather than simply promoting financial planning.
For example:
- Share educational content about preparing for retirement without a spouse or family support, including income, care expenses, and financial decision making.
- Host educational events focused on aging independently, potentially alongside estate planning attorneys, elder law attorney, or aging specialists.
- Build referral relationships with professionals who serve women experiencing divorce, widowhood, or other major life transitions.
- Start conversations with a specific question. Asking who a woman would rely on if she needed help managing her finances may uncover needs she hasn't considered.

Helping women remain independent on their terms
A self-reliant retirement doesn’t have to mean managing every challenge alone. With thoughtful preparation and the right resources, women can pursue the independence they value while knowing they’ve made arrangements for the future.
For financial professionals, it’s an opportunity to expand retirement conversations beyond savings and investments, build meaningful relationships, and demonstrate the value of guidance that addresses the full picture of retirement.
By making women aware of how you can help, you may reach an audience that needs your expertise but hasn’t yet recognized the benefit of working with you.
Looking for helpful content to share with female clients?
Related Posts

RMD Planning for Clients Who Don’t Need Their RMD
RMD planning can help clients who don’t need the income explore charitable giving strategies that may satisfy RMDs and support other financial goals.
Charitable Planning: How Financial Professionals Add Value
Explore the growing opportunity for financial professionals to add value through charitable planning, tax strategies, and multigenerational conversations.
Goals-based planning: How to connect with the next generation of clients
Learn how goals-based planning can help financial professionals connect money decisions to next-gen clients’ real-life priorities and strengthen relationships.